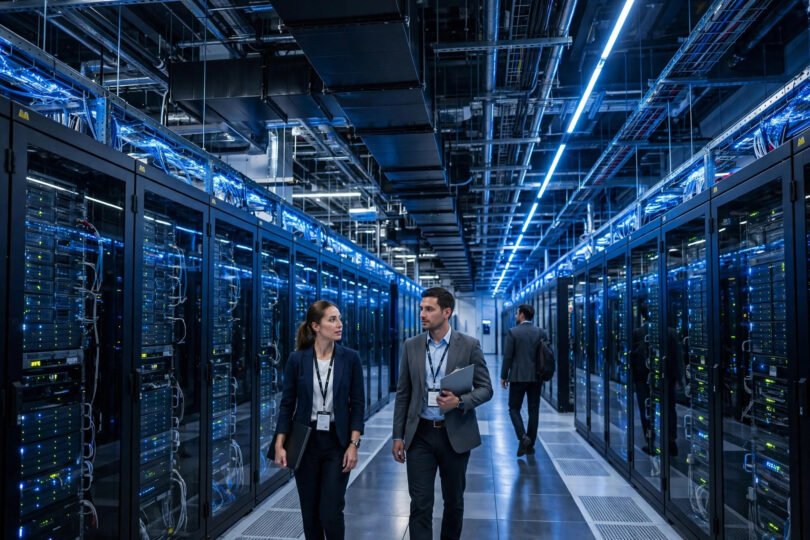

There are numbers that describe a trend, and there are numbers that stop a boardroom conversation cold. A new analysis of the artificial intelligence infrastructure boom offers the second kind. It argues that paying for the AI data-centre buildout now under way, priced at prevailing wage costs, would take the equivalent of 250 million jobs. The United States, by comparison, has about 159 million jobs in total. In other words, the labour value embedded in the current wave of AI spending is larger than the entire American workforce.
The comparison is deliberately provocative, and that is precisely its value. As the analysis published by PostQuantum sets out, translating abstract capital expenditure into jobs makes the scale of the buildout legible to executives, investors and policymakers who have grown numb to announcements measured in tens or hundreds of billions of dollars. A hyperscale campus is no longer just a construction project. Priced in labour, it is a claim on human time that exceeds what the largest economy on earth currently employs.
A Number Bigger Than the Workforce
The arithmetic works because AI infrastructure has become extraordinarily expensive at every layer. Land, power connections, steel and concrete are only the beginning. Inside each facility sit rows of advanced processors, networking equipment and cooling systems, each produced through long, labour-intensive supply chains. When the full cost of building and equipping these sites is divided by what workers are typically paid, the result is a jobs-equivalent figure that dwarfs familiar benchmarks.
Set against roughly 159 million American jobs, the 250 million figure reframes the debate. Previous technology booms, from railways to broadband, were routinely described as nation-building efforts. The AI buildout, on this measure, is larger than the nation doing the building, at least in labour terms. It also explains why the spending feels simultaneously transformative and unsettling: capital is being committed at a pace that the real economy of workers, skills and suppliers was never designed to match.
What the Comparison Really Measures
No serious analyst believes 250 million people will be hired to construct data centres, and the analysis does not claim otherwise. Much of the value flows into highly automated manufacturing, specialised chips fabricated in a handful of plants, and imported equipment. The jobs-equivalent is a measuring rod, not a hiring forecast. It answers a different question: how much human effort, at today’s prices, does this spending represent?
That distinction matters for how business leaders should use the figure, a point we return to often in our coverage at Business Journal Group. Used carelessly, the number becomes a headline in search of a panic. Used properly, it is a discipline on capital allocation. If a single technology programme absorbs resources equivalent to more than a full national workforce, then the returns required to justify it are not incremental. They must be historic, and they must arrive on a timetable that debt markets and shareholders will tolerate.
Capital Allocation Under Strain
The strain is already visible. Technology giants are funding construction with a mix of operating cash flow, corporate debt and creative off-balance-sheet arrangements involving private credit. Energy utilities are fielding connection requests that exceed the capacity of regional grids. Construction firms report shortages of electricians and specialist engineers, the relatively small slice of the 250 million jobs-equivalent that does translate into real, immediate hiring.
For investors, the question is sequencing. Revenue from AI services is growing quickly, but it is not yet growing at data-centre scale. Every quarter in which spending outruns monetisation widens the gap that future productivity gains must close. The jobs comparison sharpens that point: an economy cannot divert labour value on this scale indefinitely without either a payoff in output or a painful correction in valuations, or both.
What It Means for Labour Markets
There is an irony at the centre of the story. A technology frequently discussed as a substitute for labour is, in its construction phase, one of the largest labour-absorbing projects ever undertaken, even if much of that labour is embodied in machines rather than payrolls. The workers who are directly needed, from grid engineers to data-centre technicians, are in short supply and commanding premium wages, while the roles most exposed to automation face a very different market.
That divergence should shape workforce strategy. Companies racing to deploy AI while neglecting the skilled trades and technical roles required to run the infrastructure are building on a bottleneck. Governments, meanwhile, face a planning problem that spans energy, training and immigration policy. Readers who follow our technology coverage, from enterprise infrastructure to practical guides such as preparing your device for a gaming session, will recognise the pattern: demand arrives first, and capacity struggles to catch up.
The Bottom Line for Business
The 250 million jobs figure will be quoted, disputed and, inevitably, simplified. Its enduring usefulness is as a scale check. It tells decision-makers that AI infrastructure is not a normal capital cycle that can be judged by normal rules. Businesses buying AI capacity, selling into the supply chain, or competing for the same power and talent should plan for an extended period in which this buildout distorts prices, wages and investment across the wider economy. The companies that treat the number as a warning about concentration and timing, rather than as trivia, will be the ones best placed when the spending wave finally meets its returns.